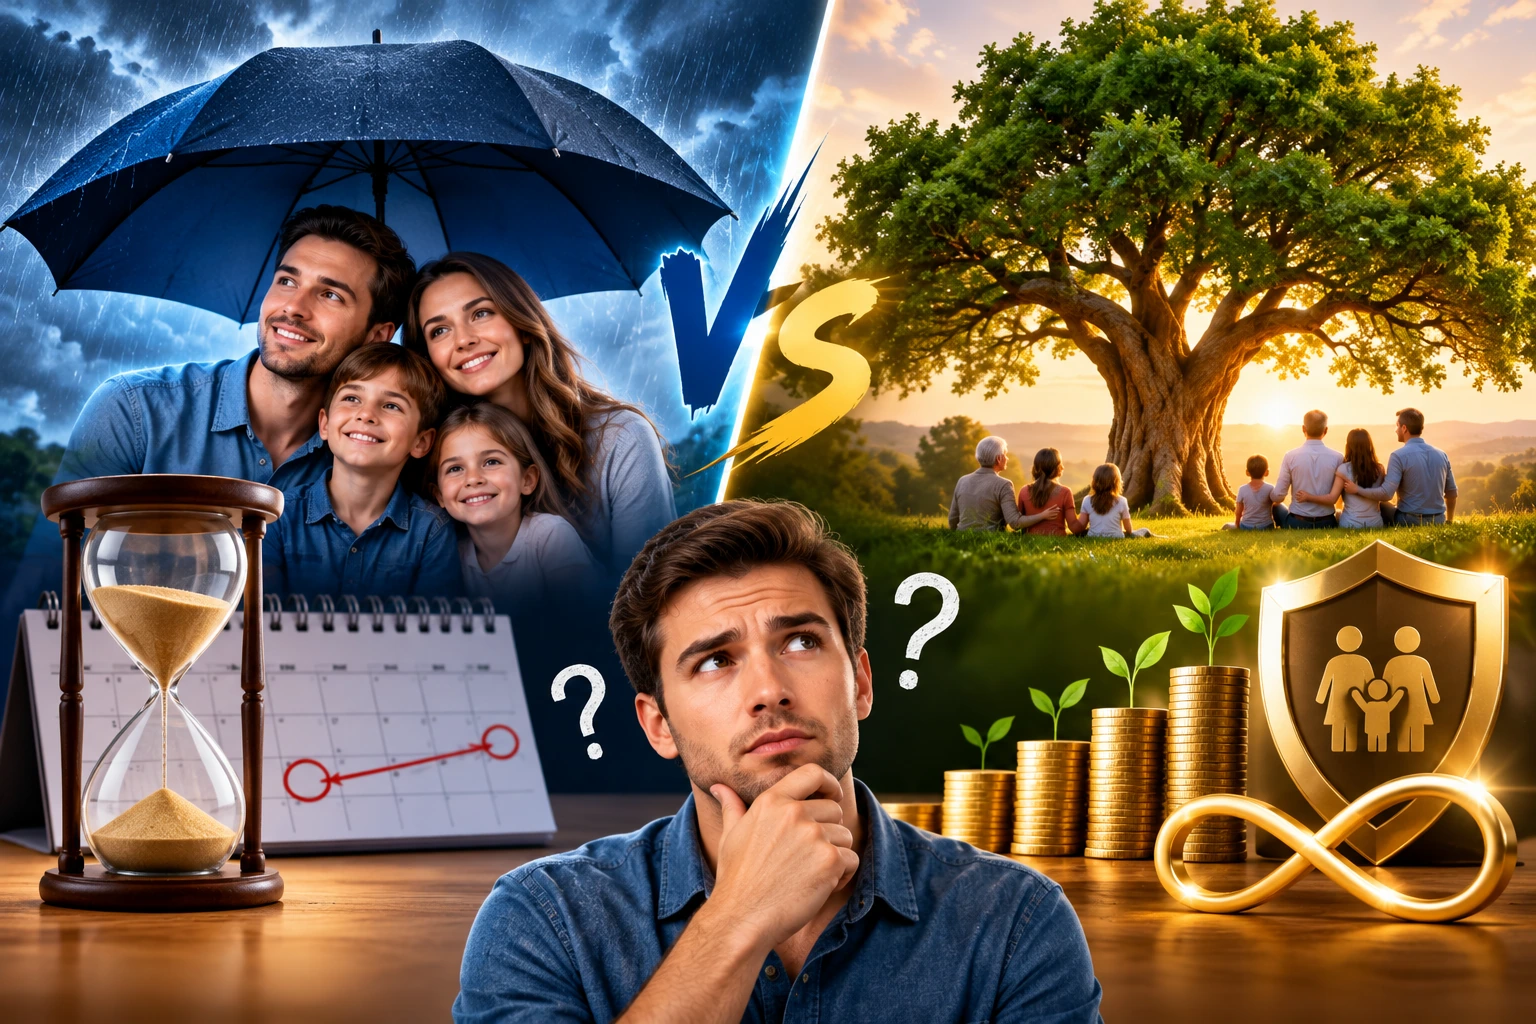
Choosing the right life insurance policy is an important step toward protecting your family’s financial future. Life insurance can help your loved ones manage everyday expenses, repay outstanding debts, and maintain financial stability if you pass away. However, not all policies work in the same way. Term life insurance and whole life insurance offer different benefits, costs, and coverage periods. Understanding these differences can help you choose a policy that matches your financial goals, family responsibilities, and long-term plans.
What Is Term Life Insurance?
Term life insurance provides coverage for a specific period, such as 10, 20, or 30 years. If the insured person passes away during the covered term and the claim meets the policy requirements, the beneficiaries receive the death benefit.
This type of insurance is generally more affordable than whole life insurance because it provides protection without a lifelong savings component.
Term life insurance can be useful for people who want to protect their families while managing significant financial responsibilities, such as a home loan, children’s education, or household expenses.
Benefits of Term Life Insurance
- Affordable premiums: Term policies generally offer substantial coverage for a lower initial premium.
- Flexible coverage periods: You can choose a term that aligns with your financial obligations.
- Family income protection: The death benefit can help replace lost income and cover essential expenses.
- Straightforward structure: Term insurance typically focuses on providing financial protection rather than building cash value.
However, coverage usually ends when the term expires unless the policy includes a renewal or conversion option. Most term policies do not build cash value, and premiums may increase if you renew coverage at an older age.
What Is Whole Life Insurance?
Whole life insurance is a type of permanent life insurance designed to provide coverage for your entire life, provided the policy remains in force and its requirements are met.
Many whole life policies include a cash value component that grows according to the contract’s terms. Premiums are generally higher than those for comparable term coverage, but the policy may offer both a death benefit and a long-term savings element.
Whole life insurance may appeal to people who want lifelong protection and are comfortable paying higher premiums over an extended period.
Benefits of Whole Life Insurance
- Lifelong coverage: Protection can continue throughout your life as long as the policy remains active.
- Cash value accumulation: Eligible policies build cash value over time.
- Predictable premiums: Traditional whole life policies typically offer premiums that remain level under the contract.
- Potential financial flexibility: Policyholders may be able to borrow against cash value or access it through permitted withdrawals, subject to policy terms.
Whole life insurance also has limitations. Higher premiums can make it harder to maintain coverage, especially when your budget is limited. Loans, withdrawals, surrender charges, and unpaid balances can reduce the policy’s value or death benefit.
Term Life Insurance vs. Whole Life Insurance: Key Differences
The main differences involve cost, coverage duration, and the availability of cash value.
Premiums: Term insurance is generally cheaper, making it suitable for people who need significant protection at a lower cost. Whole life insurance usually requires a larger financial commitment.
Coverage duration: Term insurance lasts for a selected period, while whole life insurance is designed to provide lifelong coverage if maintained according to the contract.
Savings component: Standard term policies do not accumulate cash value. Whole life policies generally do, although growth and access depend on the contract.
Financial goals: Term insurance often suits temporary responsibilities, while whole life insurance may fit people seeking permanent protection and a cash value component.
Complexity: Term insurance is usually simpler to understand. Whole life policies may require a closer review of guarantees, cash value projections, fees, and borrowing provisions.
Which Life Insurance Policy Is Right for You?
The right choice depends on your income, dependents, debts, savings, and long-term priorities.
Choose Term Life Insurance If You Want Affordable Protection
Term insurance may be appropriate if you have young children, a mortgage, or other responsibilities that will eventually decrease. For example, a parent may choose a 20-year policy to provide financial protection while children are growing up and becoming independent.
It can also be suitable for people who prefer to keep insurance costs manageable while investing separately for retirement or other financial goals.
Consider Whole Life Insurance If You Need Lifelong Coverage
Whole life insurance may suit individuals who want permanent coverage, value predictable premiums, and can comfortably afford the higher cost. It may also be considered as part of a broader estate or legacy planning strategy.
However, the cash value component should not automatically be treated as the best investment option. Compare its costs, benefits, and limitations with other financial products before making a decision.
Factors to Consider Before Buying Life Insurance
Before selecting a policy, estimate how much financial support your family would need. Consider outstanding loans, regular living expenses, education costs, and future financial goals. Subtract existing savings and other resources to help estimate an appropriate death benefit.
Also, review the insurer’s financial strength, policy exclusions, premium obligations, renewal options, and any restrictions on changing or cancelling coverage.
Your age, health, smoking status, and other underwriting factors may affect eligibility and premiums. Comparing personalized quotes can help you understand the actual cost of each option.